What Is Coast FIRE? Meaning, Pros & Who It’s For
Coast FIRE meaning in plain English: hit a Coast number today, let compounding finish the job by retirement age — plus pros, cons, and who it fits.
Coast FIRE (sometimes written Coast FI or coastfire) is a milestone on the path to financial independence: you’ve already saved enough invested assets that — if you never add another retirement contribution — market growth alone can still reach your full FIRE nest egg by the age you choose.
You usually still work to cover today’s living costs. You’re not fully retired yet. You’ve just removed the need to keep saving for retirement at the old intensity.
If you only want the number, jump to the free Coast FIRE calculator. If you want the meaning, trade-offs, and who it actually fits, keep reading.
Coast FIRE meaning in one minute
Think of three stages:
- Working & saving hard — contributions + returns build the portfolio.
- Coast — portfolio is big enough that returns alone can finish the job by your target age; you can dial contributions down (even to zero) and still fund day-to-day life from income.
- FIRE — nest egg is large enough that safe withdrawals cover your spending without needing a paycheck.
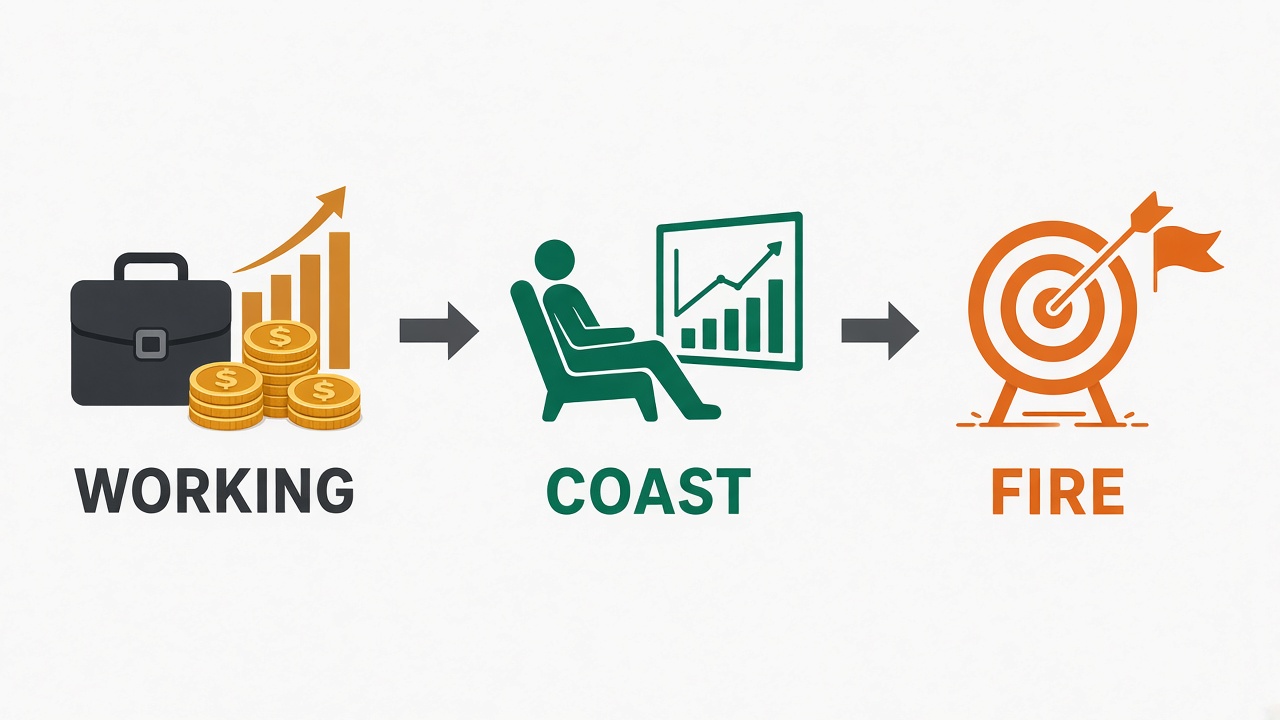
Plain-English Coast FIRE meaning: you’ve pre-funded the growth runway to retirement. Lifestyle still needs earned income until you actually stop working (or switch to Barista-style part-time work).
Related reading on this site:
- Track the invested balances that feed the plan: How to track your net worth
- See WorthCay’s Progress view in action: Demo dashboard
Coast FIRE vs traditional FIRE (visual)
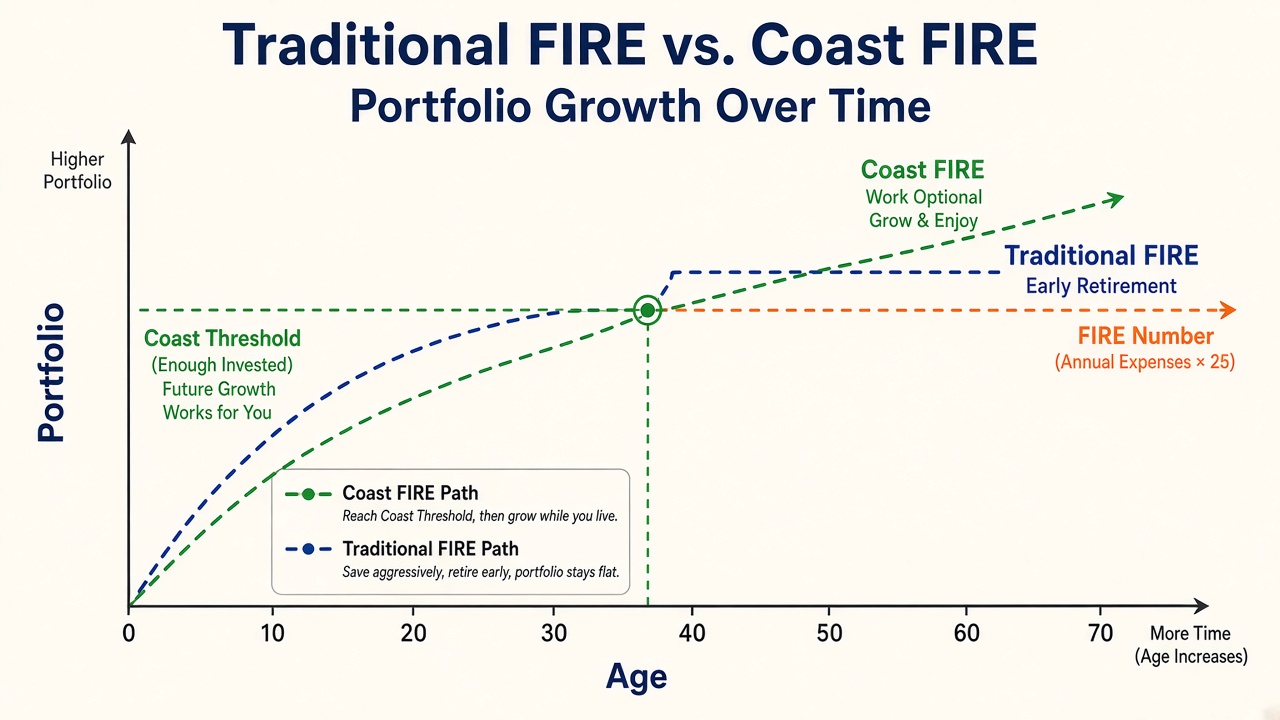
Traditional FIRE optimizes for stopping work as soon as the full nest egg exists. Coast FIRE optimizes for reaching a cheaper-today threshold, then letting time and compounding do more of the heavy lifting while you keep earning for living expenses.
| Coast FIRE | Traditional FIRE | |
|---|---|---|
| Goal soon | Hit today’s Coast number | Hit full FIRE number |
| After the milestone | Can reduce / pause retirement contributions | Can leave full-time work (in theory) |
| Day-to-day spending | Still funded by work (usually) | Funded by portfolio withdrawals |
| Pressure | Often lower savings rate later | Higher savings rate earlier |
Many people use Coast as a checkpoint, then keep contributing anyway — the milestone is optionality, not a rule that you must stop investing.
The Coast FIRE number (formula)
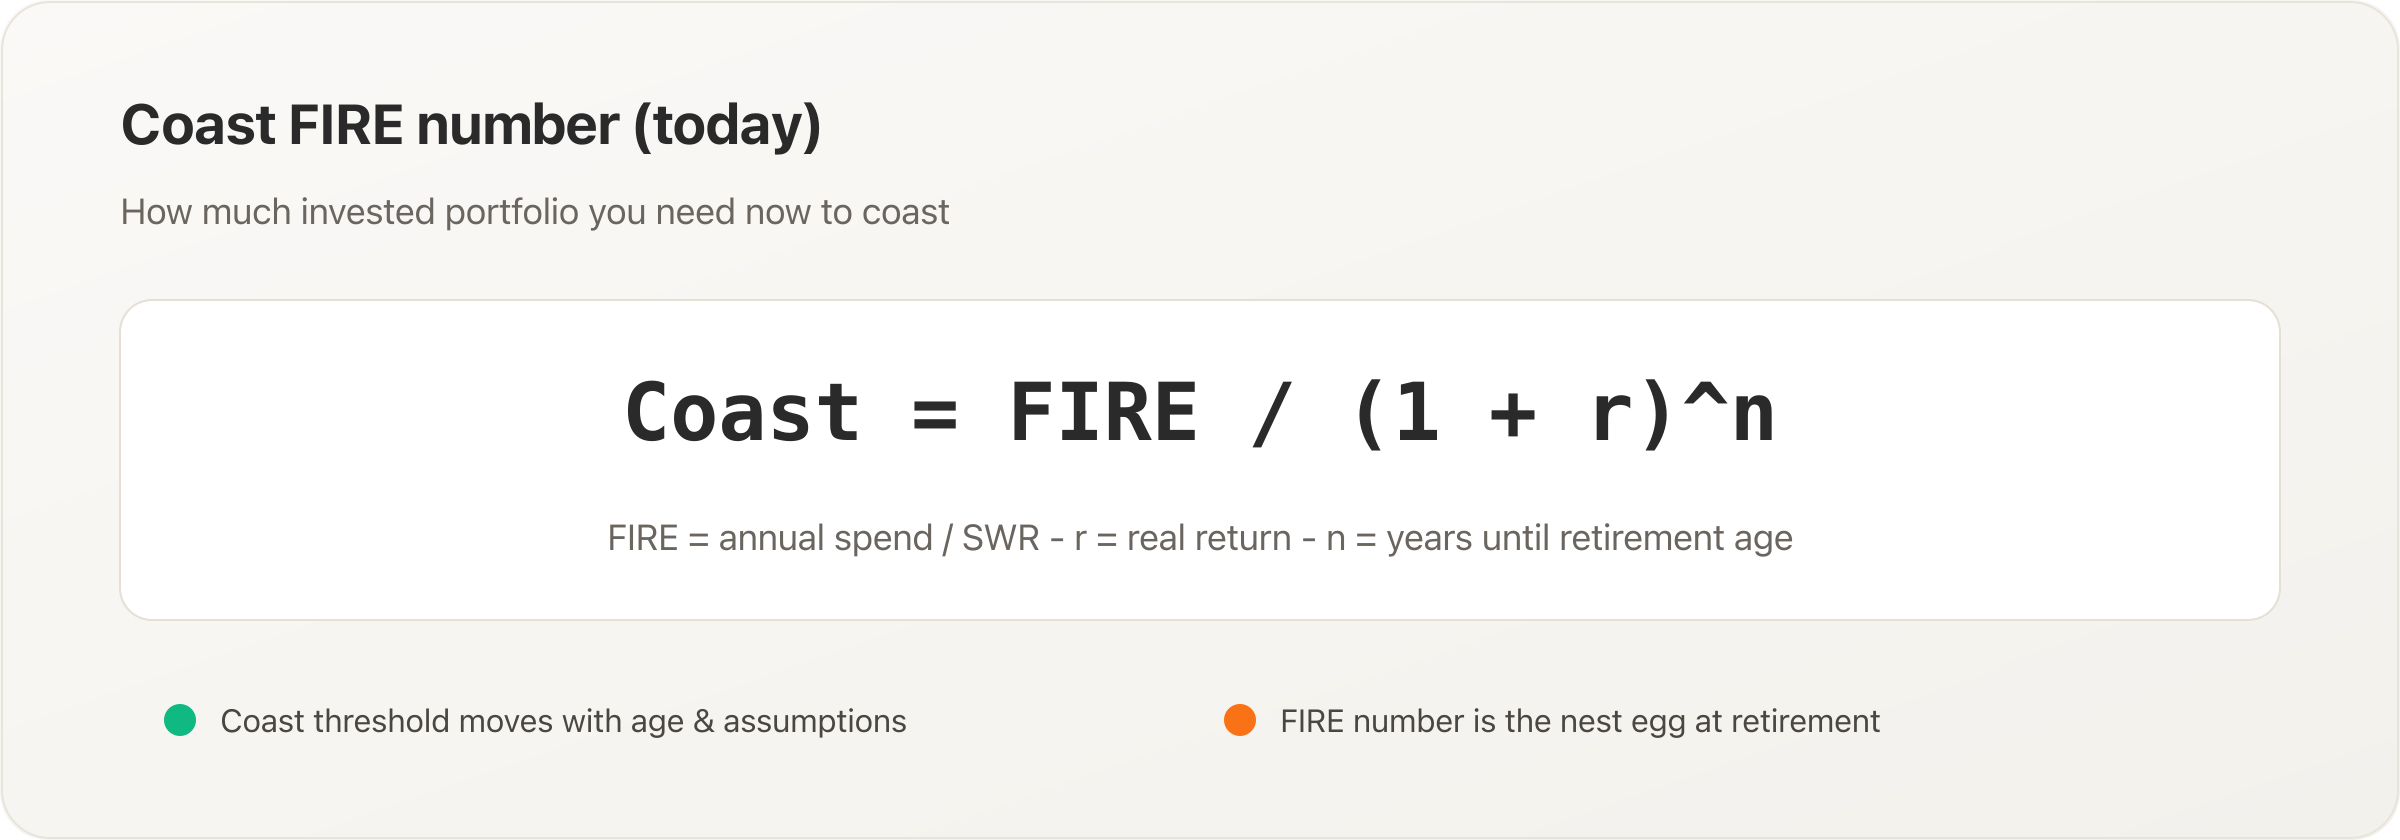
Your Coast FIRE number is a today figure: how large the invested portfolio needs to be now so that growth can reach your FIRE number by retirement age.
In practice:
- Pick annual spending in retirement (today’s dollars).
- Pick a safe withdrawal rate (SWR) — many start near 4%.
- FIRE number ≈ annual spend ÷ SWR.
- Pick years left until your target retirement age and an expected real return (after inflation).
- Coast number ≈ FIRE ÷ (1 + real return)^years.
Example (illustrative only):
- Spend $50,000/year · SWR 4% → FIRE ≈ $1,250,000
- 20 years left · ~4% real return → Coast ≈ $570,000 today (order of magnitude; your inputs will differ)
Run your inputs in the Coast FIRE calculator — then save a goal and watch Actual vs Goal in Progress as balances move.
Want the deep formula walkthrough? Read Coast FIRE Number Explained (With Formula) — or stress-test assumptions in the calculator.
Pros of Coast FIRE
- Optionality earlier — you can change jobs, take a sabbatical, or cut hours without abandoning the FI plan.
- Psychologically lighter — “I’m on the runway” beats “I must max every account forever.”
- Clear milestone — one number (Coast) plus one number (FIRE) beats a vague “save more.”
- Pairs well with real accounts — 401(k), IRA, Roth, brokerage totals map cleanly into an invested portfolio (see net worth tracking).
Cons & caveats (read these)
- You still need income for rent, food, healthcare, kids — Coast is not “quit tomorrow” unless spending is already covered.
- Assumptions matter — returns, inflation, SWR, and retirement age move the Coast line a lot.
- Sequence risk still exists later when you do withdraw; Coast doesn’t erase market risk.
- Don’t smuggle in the wrong assets — primary-home equity and short-term cash usually don’t belong in the invested FIRE total the same way brokerage and retirement accounts do.
- Life changes — kids, career shifts, and healthcare can rewrite the spending target overnight.
Who Coast FIRE is for
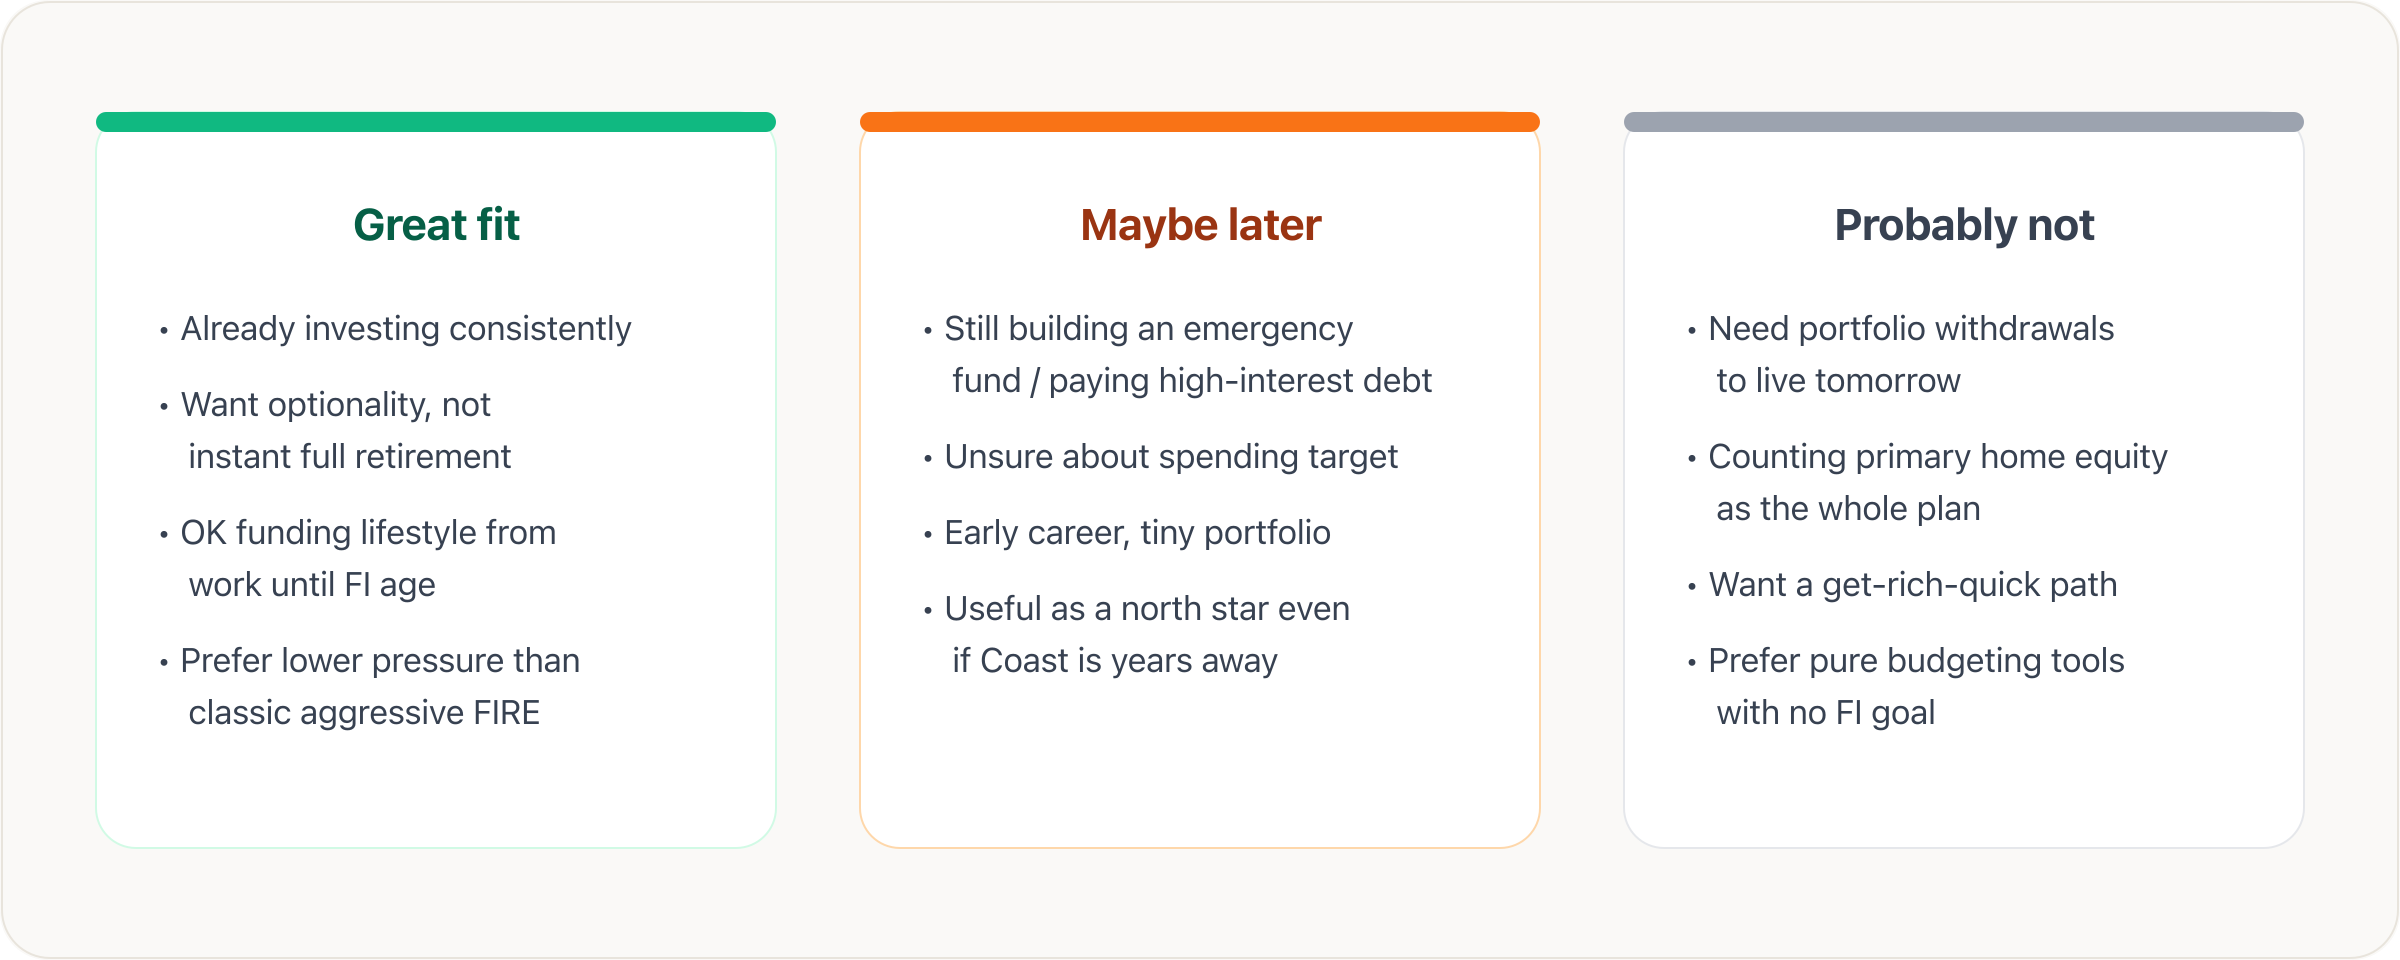
Great fit if you…
- Already invest somewhat consistently
- Want optionality more than the earliest possible quit date
- Are fine funding lifestyle from work until FI age
- Prefer a lower-pressure path than aggressive classic FIRE
Maybe later if you…
- Are still building an emergency fund or killing high-interest debt
- Don’t yet have a realistic spending target
- Are early-career with a tiny portfolio (Coast can still be a north star)
Probably not the main frame if you…
- Need portfolio withdrawals to live this year
- Are treating home equity as the entire plan
- Want a get-rich-quick story (this isn’t one)
New to WorthCay’s product angle? Start at Track your net worth with clarity, then come back to Coast math on the homepage calculator.
FAQ
What does Coast FIRE mean?
It means your invested nest egg is already large enough that, with no further retirement contributions, expected growth can still reach your FIRE number by your chosen retirement age. You typically keep working for living expenses.
Is Coast FI the same as Coast FIRE?
Yes — people use Coast FI, Coast FIRE, and coastfire interchangeably. Same idea: coast on compounding after hitting a threshold.
What is my Coast FIRE number?
It’s the today portfolio target from the formula above. Walk through the math in Coast FIRE Number Explained, or plug age, spend, portfolio, return, and SWR into WorthCay’s Coast FIRE calculator.
Do I have to stop contributing after I coast?
No. Hitting Coast unlocks the option to reduce contributions. Many keep investing to reach full FIRE sooner or to add margin of safety.
How is this different from Barista FIRE?
Barista FIRE usually means partial early retirement with part-time or lower-stress work covering a gap. Coast FIRE is specifically about the contribution runway being funded. People often combine both ideas later.
Next step
- Calculate your Coast + FIRE numbers on the free Coast FIRE calculator.
- Optional: open the demo Progress dashboard to see how Actual vs Goal looks over time.
- When balances change, keep accounts honest with net worth tracking habits.
Coast FIRE isn’t a personality type — it’s a checkpoint. Get the number, then decide how hard you still want to push.